LEGIT99 Payment Methods Australia: AUD, PayID and Bank Deposits
 Available in US
Australian banking evidence map
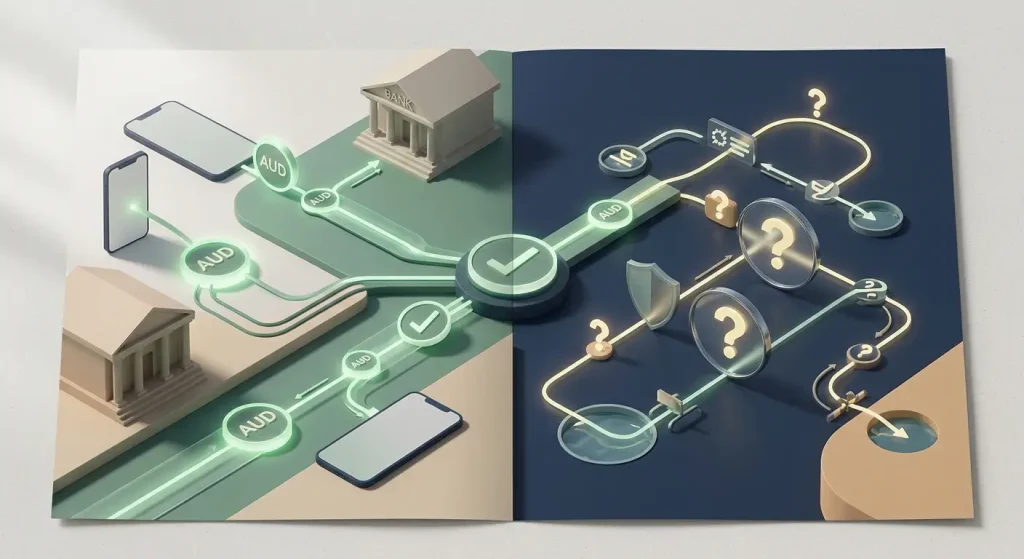
LEGIT99 supports AUD, and current independent payment listings identify five Australian-facing deposit options: PayID, Westpac Bank, Commonwealth Bank, National Australia Bank (NAB) and ANZ Bank. Those are the banking facts this page treats as verified. The same evidence does not establish that every listed deposit method is also available for withdrawals, and a current official cashier or withdrawal-terms page was not available from the sources checked. For that reason, exact withdrawal limits, fees and processing times are not published as settled facts.
The practical distinction is simple: familiar Australian deposit rails can reduce currency and banking friction, but they do not prove payout availability, Australian licensing or local dispute protection. This page separates what is known about funding from what remains unresolved about cashing out. For the broader operator context, see the full LEGIT99 review.
Table of Contents
- What is verified about LEGIT99 banking
- Why PayID is locally relevant
- Deposit methods are not automatically withdrawal methods
- What AUD support changes – and what it does not
- A banking matrix for practical decisions
- What to record before moving money
- Payment convenience does not remove operator risk
- How to audit a live cashier screen without filling gaps
- LEGIT99 payment methods FAQ
- LEGIT99 Payment Methods Australia: AUD, PayID and Bank Deposits
What is verified about LEGIT99 banking
The strongest current evidence supports two basic points: the account environment is AUD-facing, and the payment list includes PayID plus four major Australian banks. The useful way to read that list is as a record of observed deposit support rather than as a promise about every possible transaction direction.
| Banking field | Current status | What can be stated | What remains unknown |
|---|---|---|---|
| Account currency | Verified | AUD is supported | No currency conversion is needed for an AUD-denominated balance |
| PayID | Verified as an observed deposit option | PayID appears in the current payment set | Withdrawal use, fee and payout timing are not verified from official terms |
| Westpac Bank | Verified as an observed deposit option | Westpac appears in the current payment set | Withdrawal availability and transaction conditions are unresolved |
| Commonwealth Bank | Verified as an observed deposit option | Commonwealth Bank appears in the current payment set | Withdrawal availability and transaction conditions are unresolved |
| National Australia Bank (NAB) | Verified as an observed deposit option | NAB appears in the current payment set | Withdrawal availability and transaction conditions are unresolved |
| ANZ Bank | Verified as an observed deposit option | ANZ appears in the current payment set | Withdrawal availability and transaction conditions are unresolved |
| Exact withdrawal limit | Not verified from current official terms | No exact amount published here | Current official limit |
| Withdrawal fees | Not verified from current official terms | No fee figure published here | Whether a fee applies, and under what conditions |
| Withdrawal processing time | Not verified from current official terms | No speed estimate published here | Review and payment timing by method |
Why PayID is locally relevant
PayID is not a niche Australian payment label. The Reserve Bank of Australia’s 2025 Consumer Payments Survey found that around 80% of respondents were aware of PayID and around 50% had used it in the previous year. The RBA also describes PayID as a service introduced in 2018 as part of the New Payments Platform, allowing payments to be addressed through identifiers such as a mobile number or email address rather than requiring the payer to enter bank-account details manually.
That market context explains why PayID support is meaningful to an Australian reader: it is a familiar account-to-account rail rather than a foreign-currency workaround. Australian Payments Plus describes the NPP as Australia’s fast-payments infrastructure and identifies PayID as one of the services operating on it. This local relevance, however, stops at the payment rail itself. It does not turn an offshore casino account into an Australian-regulated account and it does not tell you which payout route will be offered later.
For primary background on local payment behaviour, see the Reserve Bank of Australia consumer payments research and the Australian Payments Plus NPP overview.
Deposit methods are not automatically withdrawal methods
The most important banking mistake to avoid is treating a cashier list as symmetrical. A method that can receive money from a player does not necessarily send money back to that player. Independent review data itself warns that not every listed payment method is necessarily suitable for both deposits and withdrawals. That warning is consistent with the evidence policy for this site: deposit support and withdrawal support are separate claims and require separate verification.
This matters most with the named Australian banks. Seeing Westpac, Commonwealth Bank, NAB or ANZ in a payment list shows a locally familiar deposit route. It does not prove that a withdrawal can be sent directly through the same named route, that the account must match the depositing bank, or that a payout will use the same technical rail. None of those more specific conditions is published here because current sources do not verify them from current official terms.
The dedicated LEGIT99 withdrawals page therefore treats payout questions separately. That page covers what is known about KYC, what exact payout terms remain unknown and what current complaint records show.
What AUD support changes – and what it does not
AUD support is useful because it lets the banking discussion stay in the same currency the Australian reader uses. The verified fact is the supported AUD denomination itself. This page does not invent conversions into another currency, and it does not assume that every game, promotion or transaction is free of currency-related conditions merely because the wallet supports AUD.
A locally denominated balance also should not be read as a licensing signal. Payment localisation and regulatory status are independent. A site can present Australian-dollar banking options without holding an Australian gambling licence. The separate LEGIT99 licence page handles the ACMA register and provider-side legal framework. Keeping those subjects apart prevents a common false inference: “it supports my bank, therefore it is locally licensed.”
The same separation applies to consumer protection. A payment may move through familiar Australian infrastructure while the gambling service itself sits outside Australian licensing. The bank rail tells you how funds can be transmitted; it does not by itself tell you which gambling regulator, dispute process or operator rules govern the account.
A banking matrix for practical decisions
| Method | Observed use case | AUD relevance | Verification status | Check before relying on it |
|---|---|---|---|---|
| PayID | Deposit | Australian account-to-account rail | Verified in current independent listings | Current cashier availability, withdrawal support and any transaction conditions |
| Westpac Bank | Deposit | Major Australian bank | Verified in current independent listings | Whether the exact bank option is displayed on the live account and whether it is deposit-only |
| Commonwealth Bank | Deposit | Major Australian bank | Verified in current independent listings | Current transaction direction and any account-matching requirement |
| NAB | Deposit | Major Australian bank | Verified in current independent listings | Current transaction direction and account-specific instructions |
| ANZ Bank | Deposit | Major Australian bank | Verified in current independent listings | Current transaction direction and account-specific instructions |
| Withdrawal route | Payout | Not established by the deposit list | Unresolved from official terms | Available method, limits, fees, processing stages and verification requirements |
The value of this matrix is not that it produces a longer list of payment names. It shows where the evidence changes category. The left side is supported by observed deposit data; the right side becomes a live-account or official-terms question. That dividing line is the most decision-relevant feature of the banking evidence.
What to record before moving money
This guide does not provide a deposit call to action. If you are independently reviewing a live cashier screen, record the information that can later resolve a disagreement. A simple evidence trail is more useful than relying on memory after a transaction changes status.
- Record the method shown to your account. Payment availability can be account-specific. Save the exact label displayed rather than assuming the public review list is identical to the live cashier.
- Record the transaction direction. Note whether the method appears under deposit, withdrawal or both. Do not infer payout support from a deposit icon.
- Keep the amount and AUD denomination together. This avoids later confusion about the balance currency or a quoted transaction value.
- Save any fee or limit text that is actually displayed. This page intentionally does not substitute third-party limits for current official terms.
- Preserve bank and casino references. Transaction IDs, timestamps and account history can be important if the status later needs to be reconstructed.
- Expect account verification to be a separate process. The LEGIT99 registration and KYC page explains what is established about identity checks without publishing an unsupported document list or verification time.
Payment convenience does not remove operator risk
A familiar local banking rail can make the funding side of an account easier to understand, but it should not outweigh the other evidence used to evaluate the operator. Withdrawal records, game-integrity findings, public terms, licensing evidence and complaint handling are independent signals. A payment method can be convenient even when the wider risk profile remains weak.
That is why the banking page does not turn PayID into a trust badge. The broader LEGIT99 safety review considers the additional evidence that matters after the deposit stage. Banking convenience is one input, not a substitute for that wider review.
How to audit a live cashier screen without filling gaps
A live cashier can answer questions that public review databases cannot, but only if each field is read literally. Start by identifying the section you are in: deposit, withdrawal or transaction history. Then record the method name, currency and any instructions attached to that direction. If PayID or a named bank appears only under deposits, the correct conclusion is deposit support for that account at that moment. It is not evidence of a matching payout route.
Next, separate operator information from bank information. Your bank can show whether a transfer left or reached the bank account, while the casino account shows whether a deposit was credited or a withdrawal was approved. Those are different stages. A bank-side transfer reference cannot prove that an internal casino review has finished, and a casino-side approval message does not by itself prove that funds have reached the receiving account.
Finally, treat any displayed fee, limit or processing message as time-sensitive account evidence. Save it with the date rather than converting it into a permanent rule for all users. This is particularly important here because the current public evidence verifies the deposit set but does not provide a captured official source for exact withdrawal conditions.
LEGIT99 payment methods FAQ
What currency does LEGIT99 support for Australian users?
AUD is a verified supported fiat currency in current sources.
Does LEGIT99 support PayID?
Yes. PayID is listed among the observed Australian-facing deposit options, alongside Westpac, Commonwealth Bank, NAB and ANZ.
Can I withdraw through the same bank method I used to deposit?
This page does not assume that. Current deposit-method evidence does not verify that every listed bank or PayID option is also a withdrawal method.
What are the exact LEGIT99 withdrawal limits and fees?
No exact figure is published here. Current official withdrawal terms were not captured, so exact limits, fees and processing times remain unresolved for this guide.
Does PayID support mean LEGIT99 is Australian-licensed?
No. Payment localisation and gambling licensing are separate questions. A familiar Australian payment rail does not establish an Australian gambling licence or local dispute protection.